Most people choose a life insurance plan the way they choose a mobile plan, just by the monthly price, without checking what they actually get in return. This habit is expensive in a country where life insurance penetration was just 2.7% of GDP in 2024-25. By knowing the difference between term insurance and whole life insurance, you can put every rupee of premium to best use.
In this blog, we’ll compare the two so you can choose the one that suits you.
What Is the Difference Between Term Insurance & Whole Life Insurance?
A term plan covers you for a specific period, like 20 or 30 years. If the life assured dies during the policy period, the assured amount is paid to the nominee. If the term expires before the policyholder dies, a term plan pays no benefit at the end. This is why it can provide a lot of cover at a low premium. Return of premium variants pay out the premium at maturity, but are more costly.
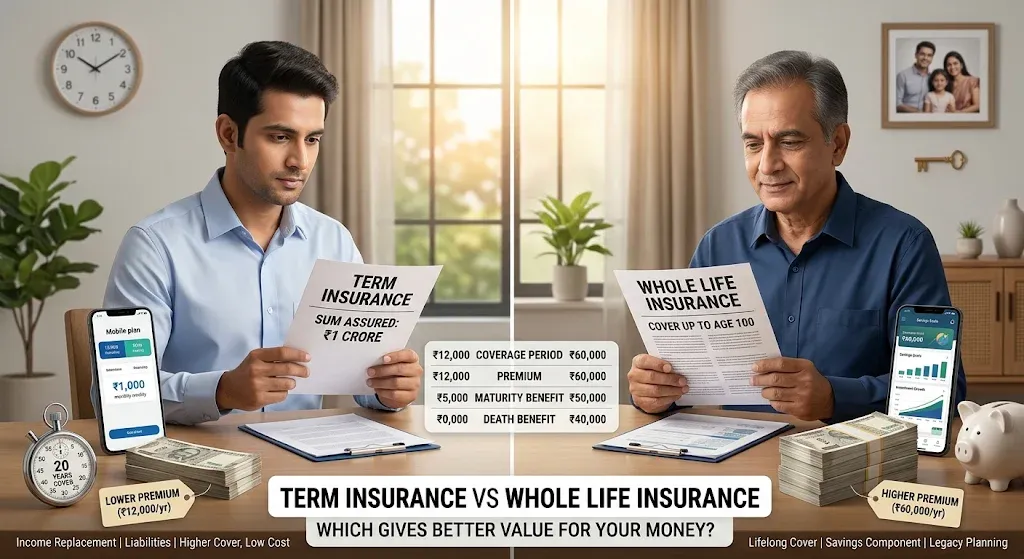
A whole life plan will continue until age 99 or 100. It provides protection alongside a savings or investment component. The “death benefit” varies according to the plan type. It can be in the form of guaranteed additions or bonuses in a participating plan or in the form of the fund value or the sum assured in a unit-linked plan.
Term vs Whole Life Insurance: How the Two Plans Compare
The table below compares term insurance vs whole life insurance to help you understand the difference clearly
| Feature | Term Insurance | Whole Life Insurance |
| Coverage period | Fixed term, such as 20 or 30 years | Up to age 99 or 100 |
| Premium | Lower for the same sum assured | Higher, as it funds lifelong cover and savings |
| Maturity benefit | None in a term plan | As per plan terms |
| Death benefit | Sum assured | Varies by plan type |
| Liquidity | None | Surrender, reduced paid-up value or loans, subject to terms |
| Best suited for | Income replacement and liabilities | Lifelong cover and legacy planning |
How to Judge “Value for Money” in a Life Insurance Plan
Cheaper is not about better value, and costlier is not about more rewarding. Three measures give this a clearer picture.
1. Cost per ₹1 crore of Cover
Divide the annual premium by the sum assured in crores to see what each plan charges for the same protection. Term plans usually win this comparison because they carry no savings component.
2. What You Get Back, and When
A term plan offers payouts only in case of claims; hence, it depends on the amount of cover. On the other hand, a whole life plan offers options to get money back during one’s lifetime in the form of surrender value, reduced paid-up, or loans. Early surrender may result in receiving less than what you paid in premiums; therefore, be careful about the surrender conditions.
3. Buy Term, Invest the Difference
Since term plan premiums are low, many people invest the savings separately in various options based on their objectives, such as mutual funds, PPF, or NPS. This provides freedom and clarity but also requires discipline. Returns on market-based products are never assured. Whole life insurance is more suitable for those buyers who want to make only one commitment.
Premium Comparison : What the Numbers Look Like
Actual premiums depend on your age, health, tobacco use, insurer, and plan. A simple example can help you compare term insurance vs whole life insurance clearly.
Suppose one person is considering ₹1 crore of cover and pays premiums for 30 years under each option.
| Term Plan (assumed) | Whole Life Plan (assumed) | |
| Annual premium | ₹12,000 | ₹60,000 |
| Total premium over 30 years | ₹3,60,000 | ₹18,00,000 |
| Premium per ₹1 lakh of cover, per year | ₹120 | ₹600 |
| Cover continues after 30 years | No | Continues up to age 99 or 100 |
| Money back during your lifetime | None | As per plan terms |
In this example, the whole life plan costs ₹48,000 more every year or ₹14,40,000 more over 30 years. That extra amount pays for lifelong cover, and the savings element & the real question is whether those two features justify the cost for you. To get real numbers for your situation, ask insurers for benefit illustrations for both plans at your age, and compare the premium per ₹1 lakh of cover along with what each plan pays out and when.
Which One Is Better for You?
Choose Term Insurance if –
You are the main earner, have dependants, or carry a home or education loan. You want the highest cover at the lowest cost, and you plan to build wealth separately. For a young, healthy earner, this is usually the practical starting point.
Choose Whole Life Insurance if –
You want lifelong cover and have already protected your income through a term plan. You value legacy planning or a structured savings habit & your budget can sustain higher premiums for many years.
Middle Paths: Return of Premium and Conversion
Two options sit between the extremes if you want low premiums but don’t like getting nothing back. A return of premium plan refunds the premiums you paid if you reach the end of the term, excluding extra premium, rider premium, and taxes, but it costs more than a regular term plan for the same cover.
The other option is conversion. Some term plans allow you to switch to a whole life policy during the term without a new medical examination. The conversion period and premiums are based on the policy, so review the policy terms before buying.
Conclusion
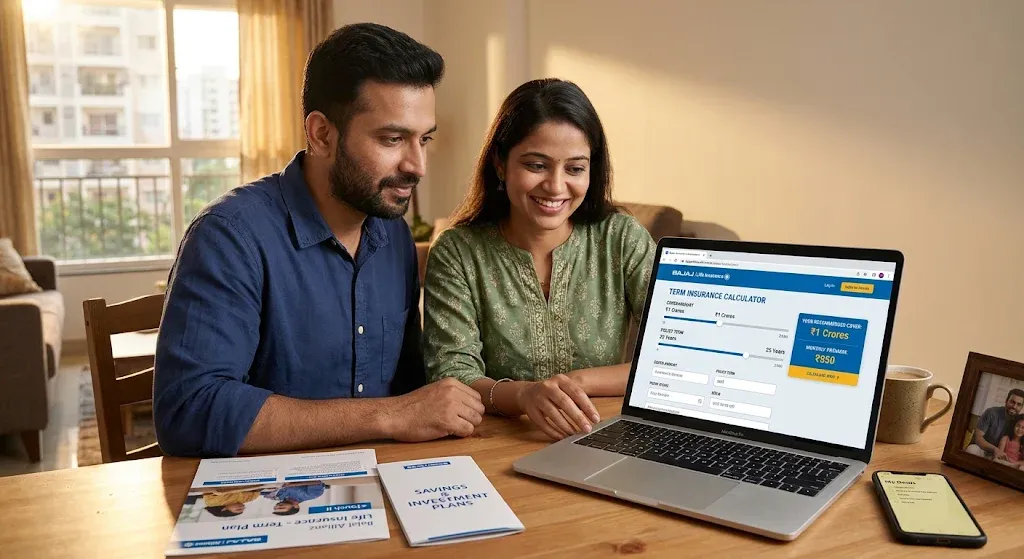
The simplest way to decide is to start with the gap in your protection. If your family would struggle without your income, a term plan fills that gap at the lowest cost, and whole life or savings plans can follow once that need is covered. Bajaj Life Insurance offers term plans such as eTouch II along with savings and investment plans, so you can compare both routes against your goals.
Use the term insurance calculator on the Bajaj Life Insurance website to see what cover fits your budget, and take the first step toward protecting your family today.
Related posts:
 What Is a Road Trading Strategy? A Trend Method for FX Beginners
 Refinancing Your Home Loan After RBI Rate Cuts: A Smart Way to Save
 Building a Scalable Business Through Accelerator Mentorship and Capital
 How Charter Bus Rentals In Brooklyn Improve The Group Travel Experience
 Industrial Asbestos Removal: What Facility Owners Need to Know Before Work Begins
Leave a Reply