Your health insurance policy is meant to provide financial protection when you need medical care. But what if you are no longer satisfied with your insurer, want better coverage, or find another policy that better suits your needs?
You do not necessarily have to give up your existing health insurance benefits and start from scratch. Health insurance portability allows you to switch from one health insurer to another while carrying certain accumulated benefits from your existing policy, subject to applicable terms and regulations.
Understanding how portability works can help you make the switch more confidently and avoid losing benefits that you may have built up over time.
What Is Health Insurance Portability?
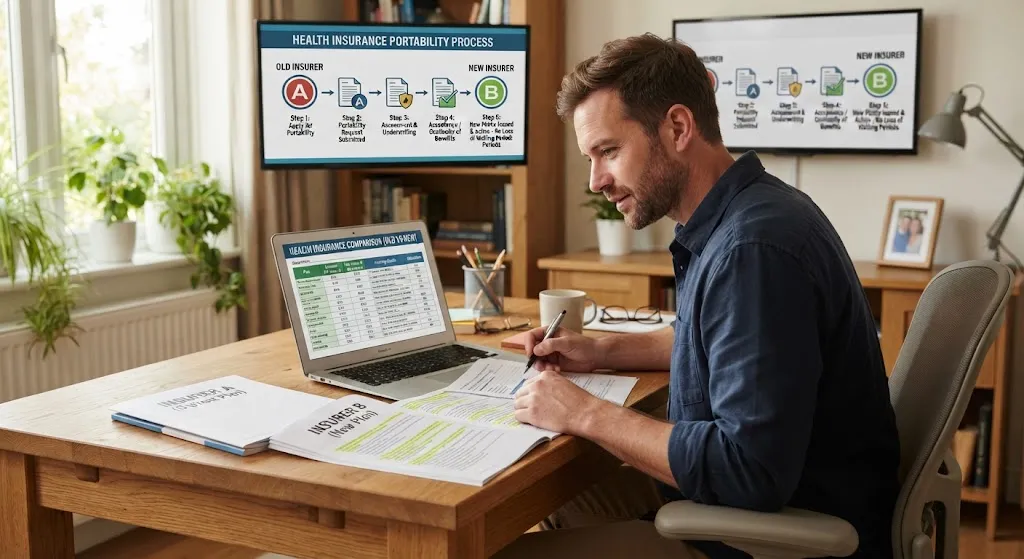
Health insurance portability is the facility that allows a policyholder to transfer an existing health insurance policy from one insurer to another without losing certain accrued benefits.
For example, if you have maintained a health insurance policy with one insurer but want to move to another insurer, you can request portability instead of purchasing a completely new policy.
Depending on the policy and applicable regulations, benefits such as credits earned for waiting periods may carry over to the new policy. However, portability does not mean that every feature, benefit, or policy condition remains exactly the same.
The new insurer will issue the ported policy according to its applicable product terms, conditions, underwriting requirements, and eligibility criteria.
Why Was Health Insurance Portability Introduced in India?
Health insurance portability was introduced to give policyholders greater flexibility and choice.
Earlier, changing insurers could be a concern because moving to a new policy could mean losing benefits accumulated under an existing policy, particularly waiting-period credits.
Portability helps address this concern by allowing eligible policyholders to move their health insurance coverage while carrying forward certain accrued benefits.
It also encourages insurers to compete on factors such as coverage, service, product features, and customer experience. This gives policyholders greater control over their health insurance decisions.
Key Benefits of Switching Your Health Insurance Plan
Porting your health insurance policy can offer several benefits when your existing plan no longer meets your requirements.
Retain Eligible Accrued Benefits
One of the key advantages of portability is that eligible credits for waiting periods can be carried forward, subject to applicable rules. This can be particularly important if you have already completed some or all waiting periods under your existing policy.
Access Different Coverage Options
Your healthcare needs may change over time. A different policy may offer features or coverage options that are more relevant to your current requirements.
Change Your Insurer Without Starting Over
Portability allows you to switch insurers without simply cancelling your existing policy and purchasing a new one. This can help preserve eligible accrued benefits.
Compare Service and Policy Features
If you are dissatisfied with your current insurer’s service or find another policy more suitable, portability gives you an opportunity to consider alternatives.
However, the decision should be based on the overall value of the new policy rather than premium alone.
Who Is Eligible for Health Insurance Portability?
Health insurance portability is generally available to policyholders who want to move from one insurer to another while continuing their health insurance coverage.
Portability is subject to the applicable regulatory framework and the terms of the policies involved. The policyholder must also follow the prescribed process and timelines.
Before initiating a request, check whether your policy qualifies for portability and whether the new insurer offers a suitable policy for your requirements.
It is also important to understand that portability is different from simply purchasing a new health insurance policy. The purpose of portability is to transfer an existing policy while carrying forward eligible accrued benefits.
What Carries Over When You Port Your Policy?
One of the most important things to understand about portability is that not every aspect of your existing policy automatically transfers to the new policy.
Eligible accumulated benefits, such as credits related to waiting periods, can generally be carried forward as permitted under the applicable regulations.
Depending on the circumstances, the portability framework may also allow eligible benefits associated with accumulated coverage to be considered when moving to the new insurer.
However, the new policy will be governed by the new insurer’s product terms and conditions.
Before making the switch, carefully compare:
- Waiting-period credits
- Existing coverage and benefits
- Sum insured
- No-claim or accumulated benefits, where applicable
- Sub-limits and deductibles
- Co-payment requirements
- Exclusions
- Room-rent limits, if applicable
- Network hospitals
- Premium
- Additional benefits and add-ons
If the new policy provides additional coverage beyond what is being ported, the additional portion may be subject to the new insurer’s applicable terms and underwriting.
Step-by-Step Process to Port Your Health Insurance
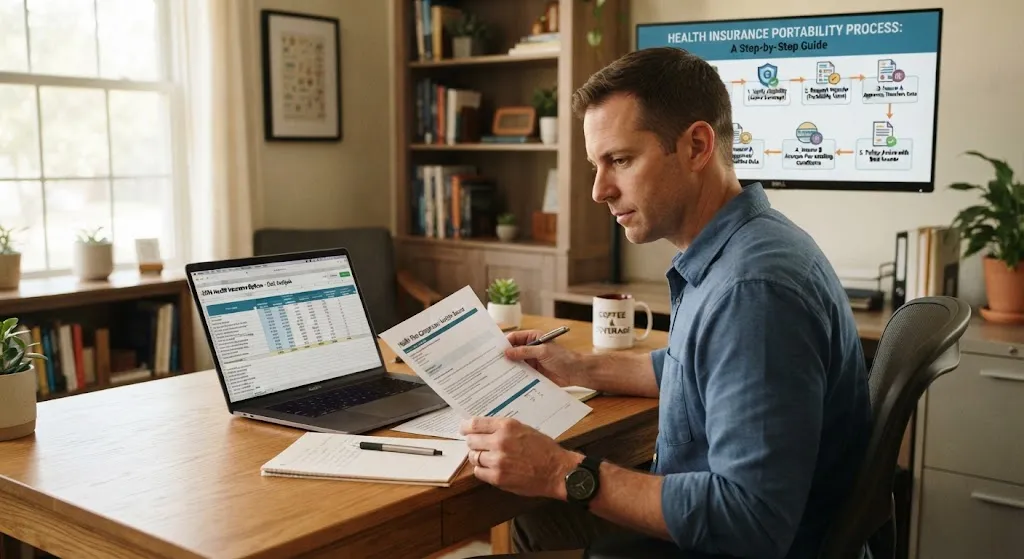
The portability process involves coordinating with both your existing insurer and the insurer you want to move to.
Step 1: Compare Your Existing and New Policy
Before initiating portability, identify why you want to switch. Compare the coverage, exclusions, benefits, premium, network hospitals, limits, and other terms of the two policies.
Step 2: Select a New Insurer
Once you have identified a suitable policy, approach the new insurer and express your intention to port your existing health insurance policy.
Step 3: Submit the Portability Request
Complete the required portability proposal and submit it to the new insurer within the prescribed timeline.
It is important not to wait until the last moment. Starting the process early gives the insurers sufficient time to complete the required formalities.
Step 4: Information Is Shared Between Insurers
The new insurer may obtain relevant policy and claims information from your existing insurer as part of the portability process.
This information helps the new insurer assess the portability request and determine the applicable terms.
Step 5: Underwriting and Assessment
The new insurer reviews the information and assesses the portability request according to its underwriting guidelines and applicable regulations.
The new insurer may determine the terms of the ported policy based on the information available and the product being selected.
Step 6: Receive the New Policy
Once the portability request is accepted and the applicable formalities are completed, the new insurer issues the policy.
Review the policy document carefully to make sure you understand the coverage, exclusions, waiting periods, limits, premium, and other applicable conditions.
When Is the Right Time to Port Your Health Insurance?
Portability is generally considered around the time of policy renewal rather than in the middle of a policy period.
If you are considering a switch, start researching well before your renewal date. This gives you enough time to compare insurers, understand the new policy, submit the portability request, and complete the required process.
You may also want to consider portability when:
- Your current policy no longer meets your coverage requirements.
- You are unhappy with the service experience.
- Another insurer offers more suitable coverage.
- Your healthcare needs have changed.
- You want access to a different network of hospitals.
- You find the terms of another policy more suitable.
However, avoid switching solely because another policy has a lower premium. A cheaper policy may have different exclusions, limits, waiting periods, or cost-sharing provisions.
Common Mistakes to Avoid When Porting Health Insurance
Porting a policy can be straightforward when planned carefully. However, certain mistakes can create unnecessary problems.
Waiting Until the Last Minute
Portability involves documentation and communication between insurers. Starting the process close to renewal can leave little time to address questions or complete formalities.
Choosing a Policy Based Only on Premium
The lowest premium is not necessarily the best option. Compare the complete policy structure before making a decision.
Ignoring Waiting Periods
Understand which waiting-period credits are being carried forward and whether any additional waiting periods apply to enhanced or additional coverage.
Failing to Disclose Relevant Information
Provide complete and accurate information during the portability process. Incomplete or incorrect information can affect underwriting and claims.
Not Reading the New Policy Document
Once the port is completed, review the new policy carefully. Do not assume that the new policy has exactly the same terms as your previous one.
Letting the Existing Policy Lapse
Do not cancel your existing policy prematurely. Follow the portability process and ensure continuity of coverage according to the applicable requirements.
Things to Check Before Choosing a New Insurer
Choosing the right insurer is just as important as deciding to port your policy.
Before switching, consider:
Coverage: Does the new policy provide the protection you need?
Sum insured: Is the coverage amount adequate for your current and expected healthcare needs?
Waiting periods: Understand what waiting periods apply and which eligible credits will carry forward.
Exclusions: Read the exclusions carefully so you know what is not covered.
Network hospitals: Check whether your preferred hospitals are part of the insurer’s network.
Claim-related features: Understand the insurer’s claim process and relevant policy conditions.
Premium: Compare the premium, but evaluate it alongside the overall coverage.
Limits and cost-sharing: Check for sub-limits, deductibles, co-payments, and other conditions that may affect your out-of-pocket expenses.
Customer service: Consider the insurer’s accessibility and service experience, particularly when you may need assistance during a claim.
When comparing options, the best insurance company is not necessarily the one offering the lowest premium. The better choice is the insurer and policy that provide suitable coverage, transparent terms, and a level of service that meets your needs.
Make an Informed Choice Before You Port
Health insurance portability gives policyholders greater flexibility to change insurers without automatically losing eligible accrued benefits. However, portability should not be treated as simply changing the name on your policy.
Take time to understand what will carry forward, what will change, and what conditions will apply under the new policy. Compare coverage, exclusions, waiting periods, network hospitals, premium, and other important terms before making your decision.
If your existing health insurance no longer fits your needs, portability can be a useful option to explore—provided you choose the new policy carefully and complete the process within the applicable timelines.


Leave a Reply