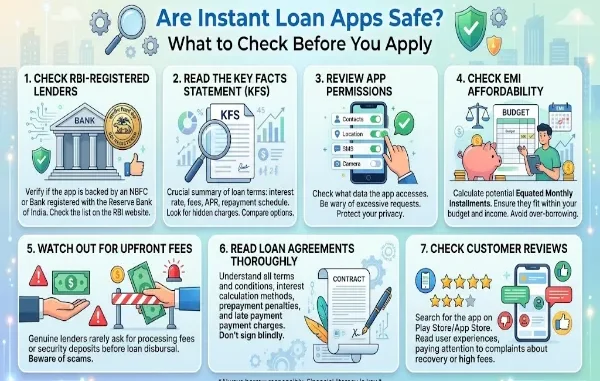
An instant loan can be useful when you need money for an unexpected expense, but getting funds quickly does not mean you should skip a few basic checks. Digital lending has made borrowing faster and reduced paperwork, but not every app offering quick loans is genuine. Some may have unclear charges, ask for unnecessary personal information, or use unfair recovery practices.
Before you apply, find out who is actually giving you the loan, how much you will repay, and what information the app wants from you. The Reserve Bank of India (RBI) also advises borrowers to check whether the lending app is connected to an RBI-regulated bank or NBFC through the lender’s website.
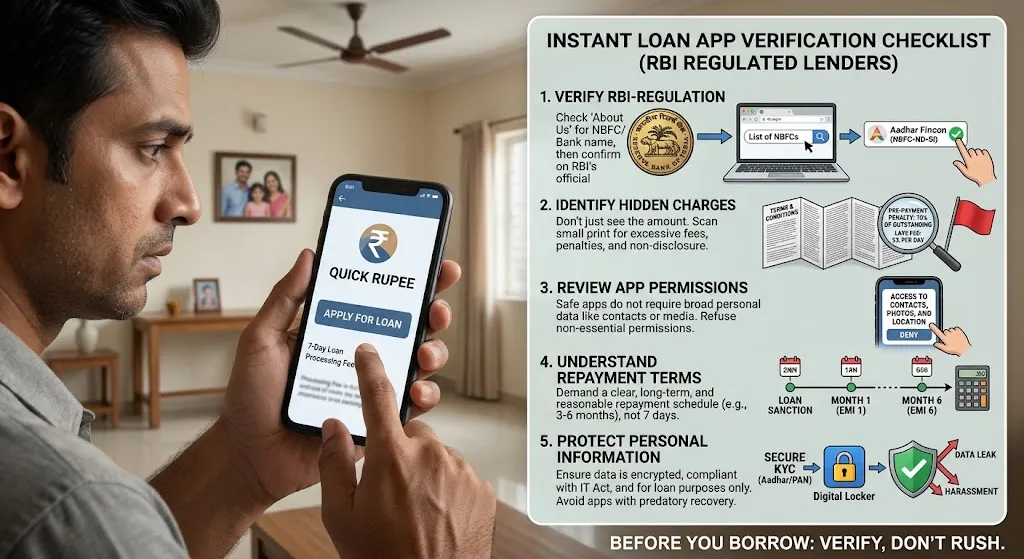
Check the Lender Behind the App
Do not assume an app is genuine just because you found it on an app store. Check the name of the bank or whether the instant loan app is partnered with RBI-registered NBFCs providing the loan.
Here are a few things to look for:
- The lender’s full legal name and contact details
- Whether the lender is regulated by the RBI
- Whether the lender’s website mentions the app or lending partnership
- Whether clear customer support and grievance details are available
The RBI also advises users not to download lending apps received through SMS or social media links.
Read the Key Facts Statement Before Accepting
Before you accept a loan, the lender should give you a Key Facts Statement (KFS). It puts important details such as the Annual Percentage Rate (APR), charges, repayment schedule, and other loan terms in one place.
Do not look at the interest rate alone. Check how much the loan will actually cost you, including processing fees and any applicable late-payment or foreclosure charges. The KFS can help you understand the overall cost before you commit to repayment.
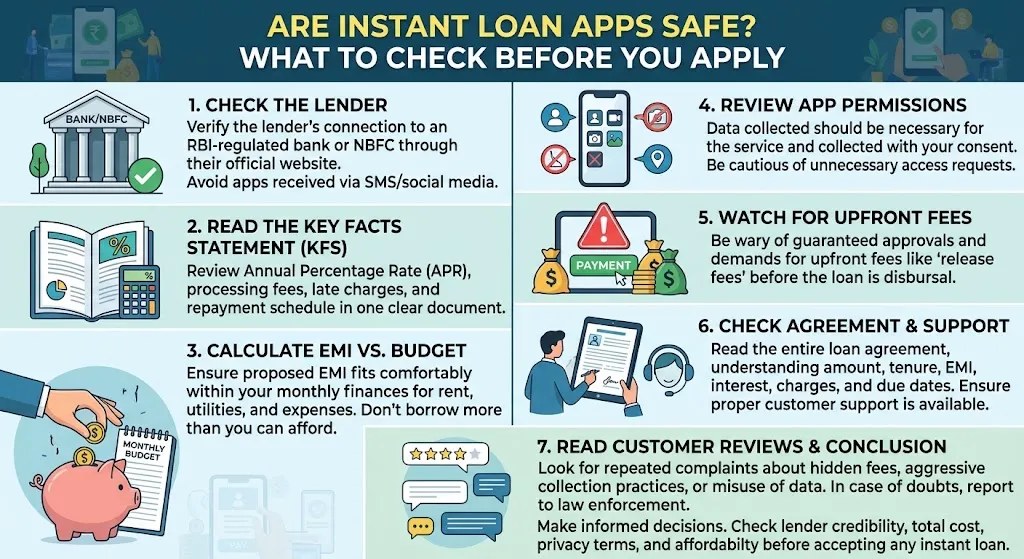
Check the EMI Against Your Monthly Budget
A quick approval does not automatically mean the loan is affordable. Prior to accepting the loan, calculate the proposed EMI with your current monthly payments in order to see how much money you would have for rent, utilities, and other regular expenses.
If the EMI results in a very thin margin in case of an emergency, consider borrowing a smaller amount or choosing a manageable tenure. A loan should fit comfortably into your budget rather than put pressure on your monthly finances.
Review App Permissions and Privacy Terms
A lending app may need some information to complete KYC and process your application, but it should not ask for access to everything on your phone. RBI rules say that data collected by digital lenders should be necessary for the service and collected with your consent.
Before allowing permissions, check:
- Why the information is being requested
- What personal data the app collects
- How your information will be used and stored
- Which permissions are optional
Be cautious if an app asks for access that does not seem connected to your loan application.
Watch for Upfront Fees and Unrealistic Promises
Be wary of those apps which offer guaranteed loan approval, unusually low interest rates, and require a payment prior to giving the loan. The requirement of upfront payment of a ‘release fee’ is a huge red flag.
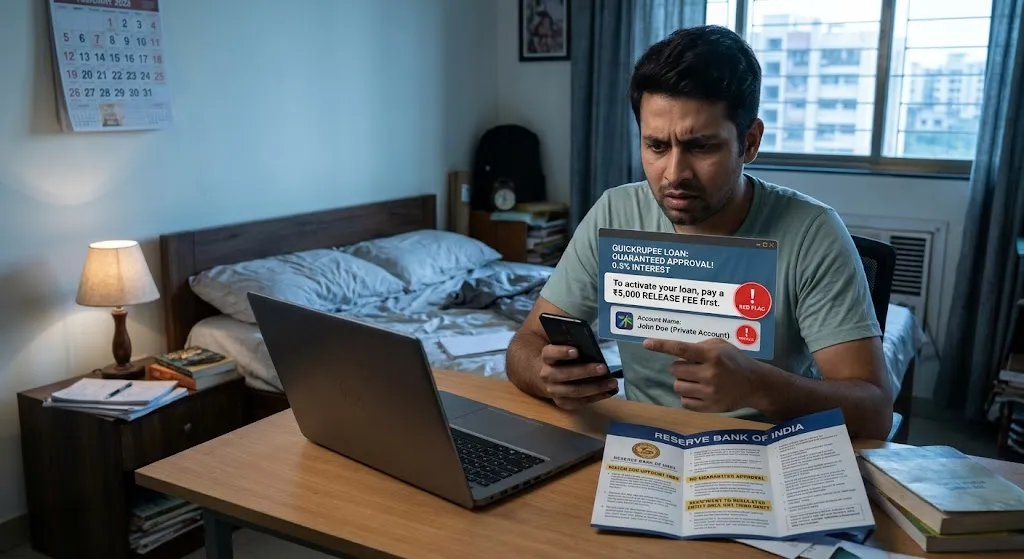
Also check whether the repayment account belongs to the disclosed lender. RBI’s framework requires digital loan disbursals and repayments to follow specified routes involving the regulated entity, rather than undisclosed third parties.
Check the Loan Agreement and Support Details
Do not sign the agreement based on the terms shown on the screen of the app. Make sure you know about the loan amount, tenure, EMI, interest rate, charges, due dates, and the implications of late repayment.
A trustworthy instant loan app should also provide proper customer support and grievance redressal. Keep all documentation, including KFS, loan agreement, receipts of payments, and other important communications till the entire loan is fully repaid.
Read Customer Reviews
Customer reviews can help you understand what other customers have experienced and spot repeated issues. Carefully consider if there are recurring problems such as hidden fees, unnecessary deductions, misuse of personal data, or aggressive collection practices.
Individual reviews may not always be reliable, so review them along with the information about the lender and regulations. In case of any doubts about the legitimacy of the instant loan app, the RBI advises reporting it to law enforcement bodies.
Conclusion
Before filling out the loan application form, spend a couple of minutes reviewing the loan provider’s website, KFS, loan agreement, and privacy policy. Make sure to check the total repayment sum, instead of considering just the advertised one. In case you spot some extra charges, unnecessary permissions, lack of lender information, or overly generous offers, pause before sharing your information or accepting the loan.
An instant loan can be convenient when you need funds quickly, but the convenience should not come at the cost of overlooking important details. Knowing who the lender is, what you will pay, how your information will be handled, and what your repayment will look like can help you make a more informed borrowing decision.


Leave a Reply