The new year brings renewed financial commitment for many people. As inflation continues to shape household budgets and economic uncertainty persists, developing concrete strategies to preserve your money has become more essential than ever. Whether you’re saving for a major purchase, building an emergency fund, or simply looking to improve your financial health, the following approaches can help you keep more of what you earn throughout 2026.
1. Automate Your Savings Before You Spend
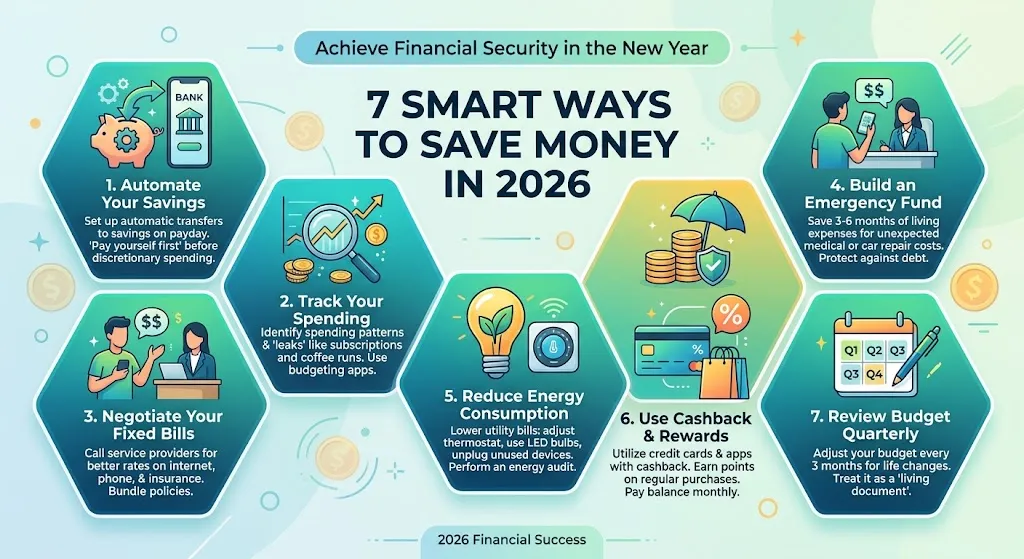
One of the most effective ways to save money consistently is to remove temptation from the equation entirely. By setting up automatic transfers from your checking account to a dedicated savings account on payday, you prioritize savings without having to think about it each month. This “pay yourself first” method ensures that money goes toward your goals before you have the chance to spend it on discretionary items. Most banks offer this feature at no cost, making it an accessible strategy for anyone with a checking account. When your savings happen automatically, you are far more likely to stick with your financial plan because the process requires no daily willpower.
2. Track Your Spending and Identify Leaks
Understanding where your money goes is the foundation of effective saving. Many people are surprised to discover how much they spend on subscriptions, coffee runs, dining out, or impulse purchases when they finally track their expenses for a month. By reviewing your bank and credit card statements, you can identify spending patterns and areas where money slips away unintentionally. Once you pinpoint these leaks, you can decide which expenses to cut or reduce. Keeping a spending journal or using budgeting apps can make this process easier and more revealing over time.
3. Negotiate Your Fixed Bills and Expenses
Your regular monthly expenses, such as insurance premiums, phone bills, and internet service, are often negotiable. Companies count on customers staying with them without questioning their rates, but a simple phone call or online chat can sometimes result in lower fees or better plans. Research what competitors are charging for similar services, then contact your current provider with this information. Insurance companies in particular frequently offer discounts when you bundle policies or maintain a clean driving record. Even small reductions in these fixed costs add up significantly throughout the year.
4. Build a Separate Emergency Fund
Establishing a dedicated emergency fund is one of the most consequential financial decisions you can make. This fund protects you from unexpected events such as medical bills, car repairs, or job loss, preventing you from going into debt when life takes an unplanned turn. Most financial experts recommend saving three to six months of living expenses in an easily accessible account. For residents navigating local cost-of-living considerations, consulting a financial advisor in Phoenix residents rely on can help determine an emergency fund target that reflects your specific income, expenses, and regional economic conditions. Starting with as little as fifty dollars per month still represents meaningful progress toward this crucial safety net, and once the fund reaches its target, those monthly contributions can be redirected toward other savings goals entirely.
5. Reduce Energy Consumption and Utility Costs
Your utility bills represent a significant portion of monthly household expenses, yet they often go overlooked in budget discussions. Making simple changes such as adjusting your thermostat by a few degrees, switching to LED light bulbs, running full loads of laundry, and unplugging devices when not in use can lower your electric bill noticeably. Many utility companies offer energy audits, sometimes free of charge, to identify where your home is losing energy efficiency. Weatherstripping doors and windows, insulating pipes, and fixing leaks can also contribute to lower water and heating bills. These changes benefit both your wallet and the environment.
6. Take Advantage of Cashback and Rewards Programs
If you pay for purchases using credit cards or shopping apps, using platforms that offer cashback or rewards can return a percentage of your spending directly to you. Many retailers offer loyalty programs that provide points or discounts on future purchases, effectively reducing your overall spending over time. Credit card rewards can be especially valuable if you pay off your balance each month and avoid interest charges. Some cards offer bonus points for specific spending categories such as groceries or gas, allowing you to maximize returns on purchases you make regardless. The key is using these programs intentionally and not spending more simply to earn rewards.
7. Review and Adjust Your Budget Quarterly
A budget written in January may no longer reflect your financial reality by April. Life changes such as a raise, a new expense, or a paid-off debt can all shift the numbers in meaningful ways. Reviewing your budget every three months gives you the opportunity to reallocate funds, increase savings contributions, and ensure your spending still aligns with your priorities. This practice also keeps you engaged with your financial plan rather than setting it aside and forgetting it. Treating your budget as a living document rather than a fixed rule makes it far more useful as a long-term tool.
Conclusion
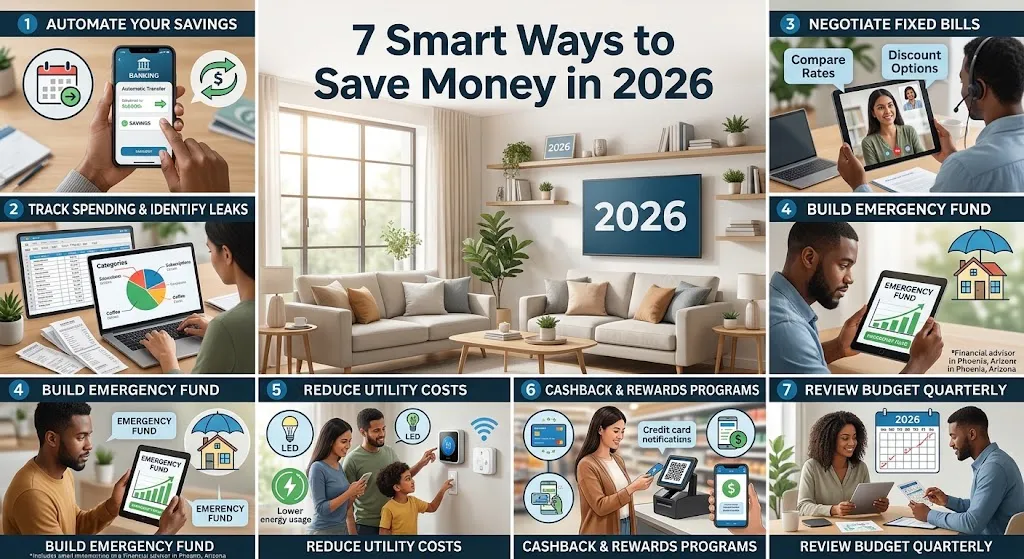
Saving money in 2026 does not require dramatic lifestyle changes or unrealistic sacrifices. By implementing these seven strategies, you can build consistent savings habits that align with your financial goals and values. Start with one or two approaches that resonate most with your situation, then gradually add others as they become routine. The most successful savers treat their financial health with the same importance they give to their physical health, making it a priority and checking on progress regularly. Your future self will benefit from the effort you invest in your finances today.
Related posts:
 Understanding Long-Term Disability Claims in Michigan and Workplace Injury Legal Support
 Canada Visa for Indians Planning a Summer in the Great White North
 How VR Porn Is Challenging Traditional Views on Sex and Connection
 Creative Ways To Use Your Outdoor Space
 The Biggest Furniture Trends in the US Right Now (And It’s Not What You Think)
Leave a Reply